Cash Drawer, Bank Bag, and Daily Settlement Controls
LEDGER · August 9, 2026
Assign the drawer before the first transaction
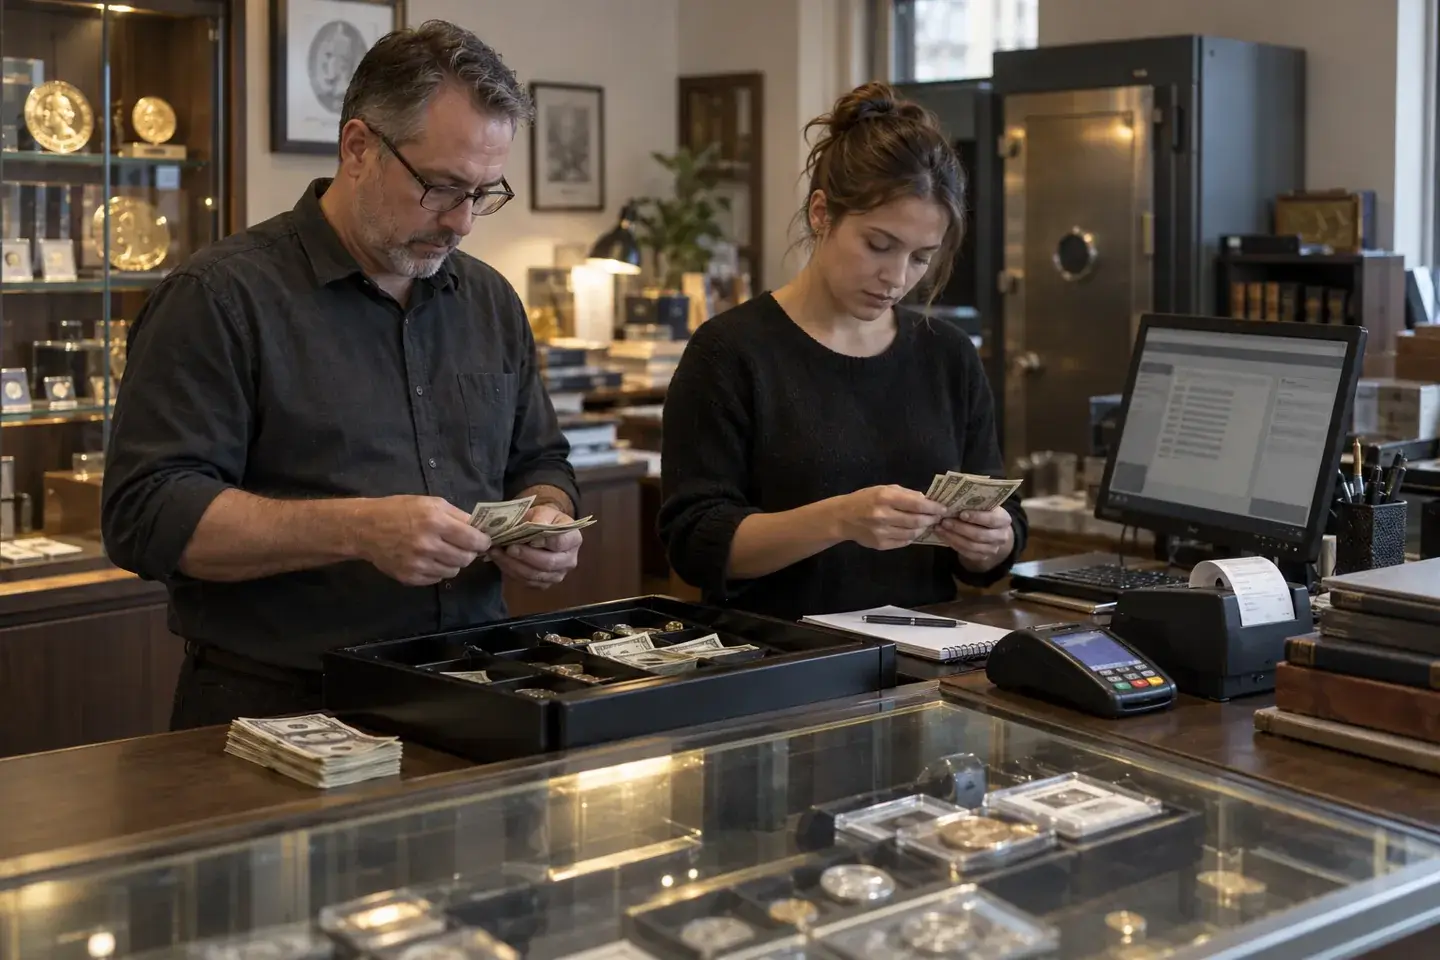
Each drawer or cash workstation should have an opening amount, an assigned employee or controlled team, and a documented count by denomination. Shared responsibility without a handoff record makes shortages harder to investigate and trains staff to treat variance as normal.
When a drawer changes hands, count it and record the transfer. The next employee should not inherit an unexplained difference.
Record buy payouts and sell receipts differently
A customer selling metals to the shop and a customer buying metals from the shop create opposite cash flows. The transaction record should make direction unmistakable and connect the payout or receipt to the client, exact items, pricing decision, and required documents.
- Use defined payment-method names instead of free-form notes.
- Separate cash received, cash paid, checks, cards, wires, ACH, credits, and other approved methods.
- Record split payments explicitly.
- Keep pending or failed payments out of settled totals until their actual status changes.
- Require approval for large payouts, manual refunds, and off-policy payment changes.
Control bank bags and deposits as custody items
A deposit bag is a custody container. Give it a unique reference, record who prepared and verified it, list the included drawer or transaction totals, seal it, and document every handoff through bank acceptance or the approved end state.
Do not allow “taken to the bank” to become the final status. The operating record should show who transported the bag, when it left, and the evidence that completed the deposit.
Reconcile by method, then reconcile the whole day
Start with expected activity from completed transactions. Compare each payment channel to its independent evidence: physical count for cash, checks on hand, processor totals for cards, and bank or payment status for electronic methods.
Then compare money to documents and inventory. A correct card total does not resolve an invoice attached to the wrong client. A correct cash count does not resolve purchased gold left in an undefined location.
| Control | Compare | Common exception |
|---|---|---|
| Cash | Opening + receipts – payouts – drops | Unrecorded payout or wrong method |
| Checks | Checks on hand to recorded payments | Missing reference or duplicate entry |
| Cards | Processor batch to settled transactions | Void, refund, or pending authorization |
| Deposit | Bag contents to deposit record | Handoff or bank evidence missing |
| Metals | Transaction items to physical movement | Correct payment, wrong custody location |
Never force a variance to zero
An adjustment can make a report look balanced while destroying the evidence needed to find the cause. Record the original expected amount, the observed amount, the variance, the employee or station, and the steps taken to investigate.
Assign an owner and review deadline. If a correction is justified, preserve the reason and approval. Repeated small differences can reveal a training, process, device, or authorization problem long before the total becomes material.
Turn settlement into an owner dashboard
Daily totals should make open payments, refunds, payout approvals, deposit status, and unresolved variances visible without exposing employees to more financial access than their roles require.
That gives owners a current operating picture and gives finance a cleaner starting point for the month-end close.